A practical guide to growing mushrooms in IndiaA joint educational initiative by MushroomWale & DMR Solan ↗
MushroomFarming.in

A joint educational initiative by

MushroomWale.com
ICAR–Directorate of Mushroom Research, Solan logoICAR–DMRSolan

MushroomFarming / guide

How to work out mushroom farming cost and profit

Understand investment, operating cost, production, market risk, working capital and profitability before committing capital.

4 full chapters + technical referenceSources & review ↓
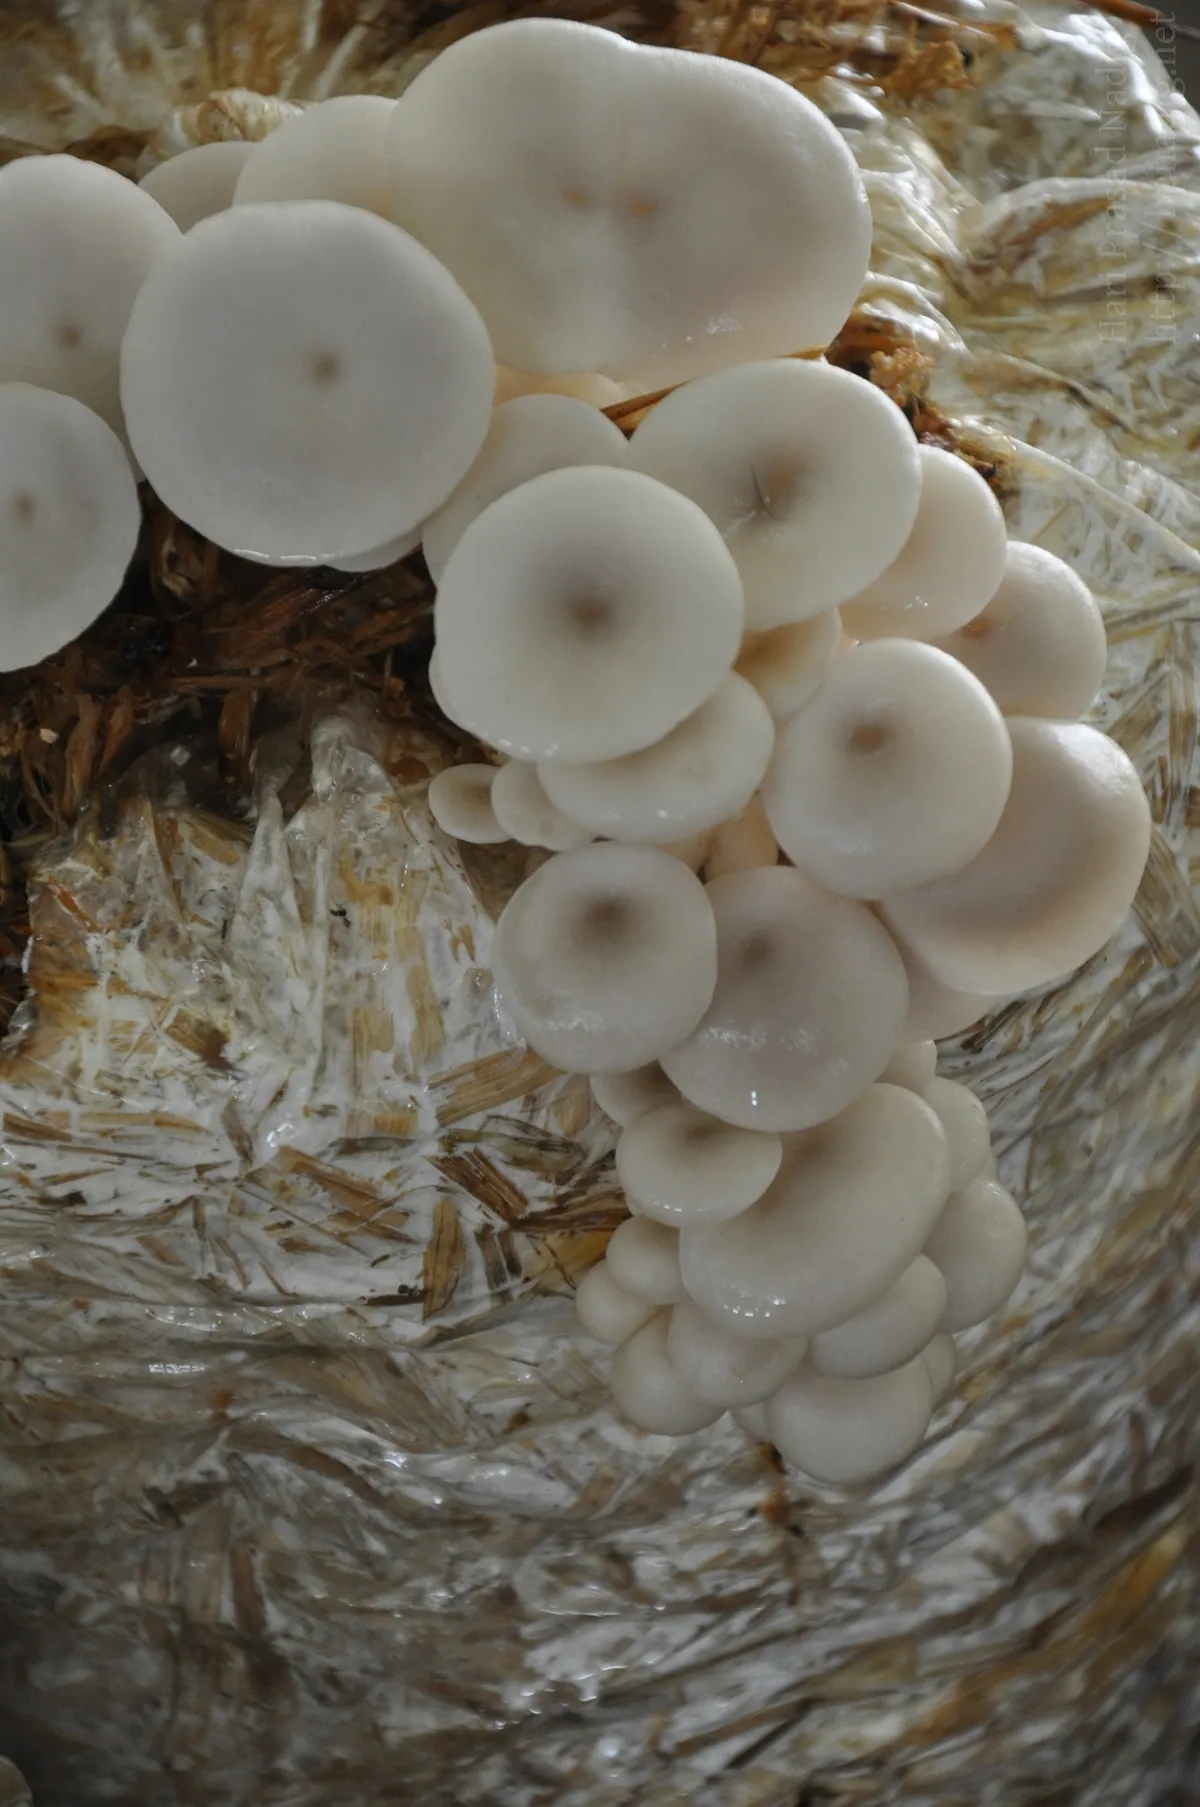
White oyster mushrooms fruiting from a paddy-straw bag, displayed at an organic food mela in Bangalore, Karnataka (2010).
Real cultivation photograph. Read its source for location and context; it is not a universal operating specification.Hari Prasad Nadig from Bangalore, India · CC BY-SA 2.0View full photograph ↗
On this pageChoose a section, or keep reading below
The full field guide

Calculate a crop's costs, sales and cash requirement

Follow the money from inputs to accepted sales and collected payments. Use a worked example without mistaking it for an earnings promise.

Choose a picture to understand that part of the process.

  1. 01Assets and running inputs
  2. 02Harvest is not all sold
  3. 03Try a weaker result
  4. 04Follow the payments

AI-generated teaching illustrations · Not photographs of actual farms

Chapter 01

Define what the calculation includes

Begin with one named crop, one production system and one period. State whether you buy compost or make it, own or rent the building, and sell at the farm or deliver. Otherwise two cost-per-kilogram figures can describe entirely different businesses. Record the units behind each input: dry straw, wet substrate and delivered compost are not interchangeable quantities.

Separate investment from operating expenses. Building work and equipment create assets; substrate, power, packaging and routine labour support production. Include maintenance, owner labour and shared costs explicitly. For a profitability view, account for asset use and financing with a qualified adviser. For cash planning, record when the actual payments fall due. A capital purchase and its depreciation must not both be deducted as the same period's operating expense.

Keep four records rather than one profit number
RecordWhat goes in itQuestion it answers
Investment registerAssets, installation, delivery, taxes and exclusionsWhat must be funded before operation?
Crop cost sheetInputs, labour, utilities, packing and allocated overheadWhat did this crop consume?
Sales ledgerAccepted grades, quantities, prices, returns and deductionsWhat revenue was earned?
Cash calendarActual and expected receipts, payments and loan instalmentsCan the farm pay its bills on time?
Chapter 02

Reconcile the kilograms before calculating revenue

Weigh harvest and record where it goes: sold, held as stock, rejected, used as samples or lost. Split sales by grade and buyer because prices and deductions differ. Revenue from accepted credit sales and cash received are separate measures; an unpaid invoice may be a receivable, not an immediate cash receipt. Returns and bad debts need their own treatment.

Use the denominator that matches your question. Production cost per harvested kilogram describes production. Cost per sold kilogram also exposes unsold and rejected output. Cash collected per kilogram describes collections, not the biological performance of the crop. Label the period so that a payment received this month for last month's crop does not distort this crop's result.

Worked example · invented teaching inputs

100 kg harvested does not mean 100 kg sold.

  • 60 kg · Grade A
  • 30 kg · Grade B
  • 10 kg · Rejected / unsold
Grade A60 × ₹150₹9,000
Grade B30 × ₹110₹3,300
Sales revenue90 kg sold₹12,300
Operating result

₹12,300 revenue − ₹10,800 operating cost

₹1,500 surplusBefore financing, tax and any other omitted costs.
Cash position

₹10,300 collected − ₹10,800 paid

₹500 cash shortfall₹2,000 remains unpaid by buyers.

Hypothetical quantities and prices, not a yield forecast, current quotation or income promise.

Chapter 03

Test a weaker crop and a slower buyer

Change one assumption at a time to understand what drives the result, then test a combined difficult case. Lower saleable output, weaker grade mix, higher electricity expense and slower collections affect different parts of the model. Do not reduce yield while leaving the same kilograms sold in the sales table. That creates revenue unsupported by production.

A break-even calculation is useful only when its assumptions are explicit. At an assumed selling price of ₹140/kg and variable cost of ₹90/kg, contribution is ₹50/kg. With ₹15,000 of period fixed costs, operating break-even is 300 kg sold. If price does not exceed variable cost, selling more does not cover fixed costs under that model. This simple example excludes financing, tax and capacity constraints; it is not a project appraisal.

Chapter 04

Fund the gap between paying for inputs and collecting sales

Put anticipated receipts and payments onto a weekly calendar through preparation, growing, harvest and buyer payment. The largest cumulative cash shortfall is the starting point for working-capital planning, with a justified contingency. Include the next batch: selling the first crop does not remove the need to buy inputs for the following one.

Check the calendar against actual bank and buyer terms before borrowing or committing to expansion. Keep a no-subsidy operating case and a delayed-start case. Review the first complete crops against the original assumptions and update the model with observed quantities rather than increasing the forecast to match a desired income.

Chapter sources & scope

These are educational explanations, not an independently reviewed operating protocol. Worked examples do not predict your yield or income.

  • NHB mushroom DPR model (2018) ↗

    Historical project-report structure, not current eligibility, prices or sanction. Worked examples below are original and hypothetical.

Back to the chapter list ↑

Understand the topic

What you need to know.

This page teaches the method for working out what a mushroom farm will cost to build and run, what each saleable kilogram costs, and how much cash must be ready before buyers pay. It is written for a grower or first-time investor who wants to test a plan before spending. It gives no profit figure. Your own quotations, bills, crop records and buyer rates decide the answer, and an honest answer can be no.

Teaching revised 2026-09-24. Source-linked editorial synthesis; this date does not imply independent technical review.

Part 01

Sort every rupee: spent once, spent every crop, or held as cash

The ICAR-DMR manual divides spending on a mushroom farm into two groups. Fixed assets are items that last longer than one crop: land, building, boiler, blowers, compost handling equipment, air-conditioning equipment and shelves. Recurring expenditure is what each crop uses up: compost ingredients, spawn, casing soil, energy, pesticides, labour and salaries. Planners call the first group CAPEX and the second OPEX.

Add a third column of your own: working capital. It is not a third kind of cost. It is cash that must sit ready because straw, spawn and wages are paid weeks before any buyer pays you.

Put every quotation and bill you hold into one of the three columns, with the date you expect to pay it. Count a capital item only once. When the manual works out its cost of production, it adds interest and depreciation on land, building and machinery to raw materials and wages, so money spent on the building comes back as a yearly charge. Do not also deduct the full purchase price in the same year's operating cost, or the building is counted twice.

Source: ICAR-DMR manual, 2011

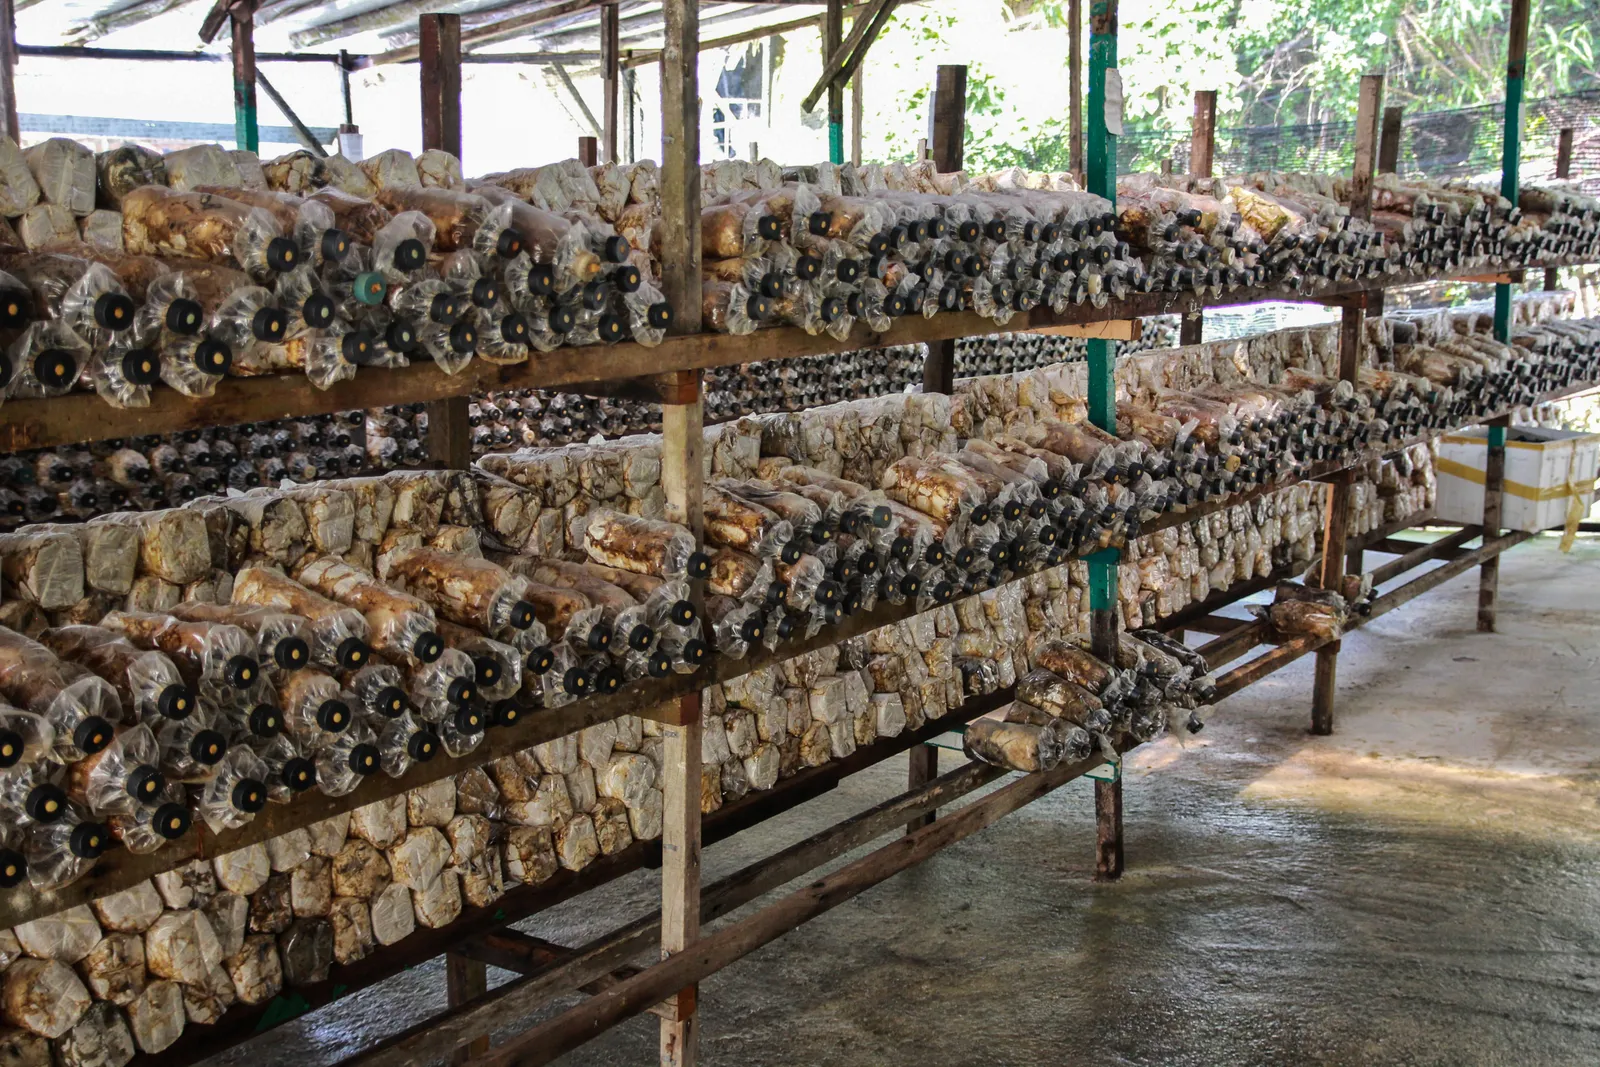
Rows of tiered racks holding sawdust substrate bags with bottle-neck collars in an open-sided mushroom shed, Cameron Highlands, Malaysia.
An open-sided shed in Malaysia with long wooden racks of sawdust substrate bags. The shed and racks are paid for once; the bags on them are bought again for every crop. Photo: Arne Müseler, CC BY-SA 3.0 de. Source
Part 02

Work out cost per saleable kilogram, step by step

A cost per kilogram means something only when you say what is inside the cost and which kilograms you divide by. Work from one finished crop with every bill kept.

  1. Draw the boundaryName the crop, the growing system and the period. Say whether compost is bought or made, the building owned or rented, and the produce sold at the farm or delivered. Two cost figures with different boundaries cannot be compared.
  2. Total the costs in three layersMaterials used up each crop (compost or straw, spawn, casing, bags); costs spent each crop (labour, power, fuel, water, packing, transport, commission); and costs that run all year (rent, depreciation, interest, your own salary). Value family labour at the local wage.
  3. Weigh where the harvest wentRecord kilograms picked, then kilograms sold by grade, held, rejected, given as samples or lost. Only kilograms a buyer accepted become sales.
  4. Divide by kilograms soldThe ICAR-DMR manual's 2011 model for a plant of 500 tonnes a year produces 518.4 tonnes at 18 per cent conversion (18 kg of mushrooms per 100 kg of compost) but counts 500 tonnes accepted, and its cost per kilogram works out on the accepted tonnes. Divide your own total the same way.
  5. Compare with cost per picked kilogramDivide the same total by kilograms picked. The gap between the two figures shows what grading losses and unsold stock are costing you.

Source: ICAR-DMR manual, 2011

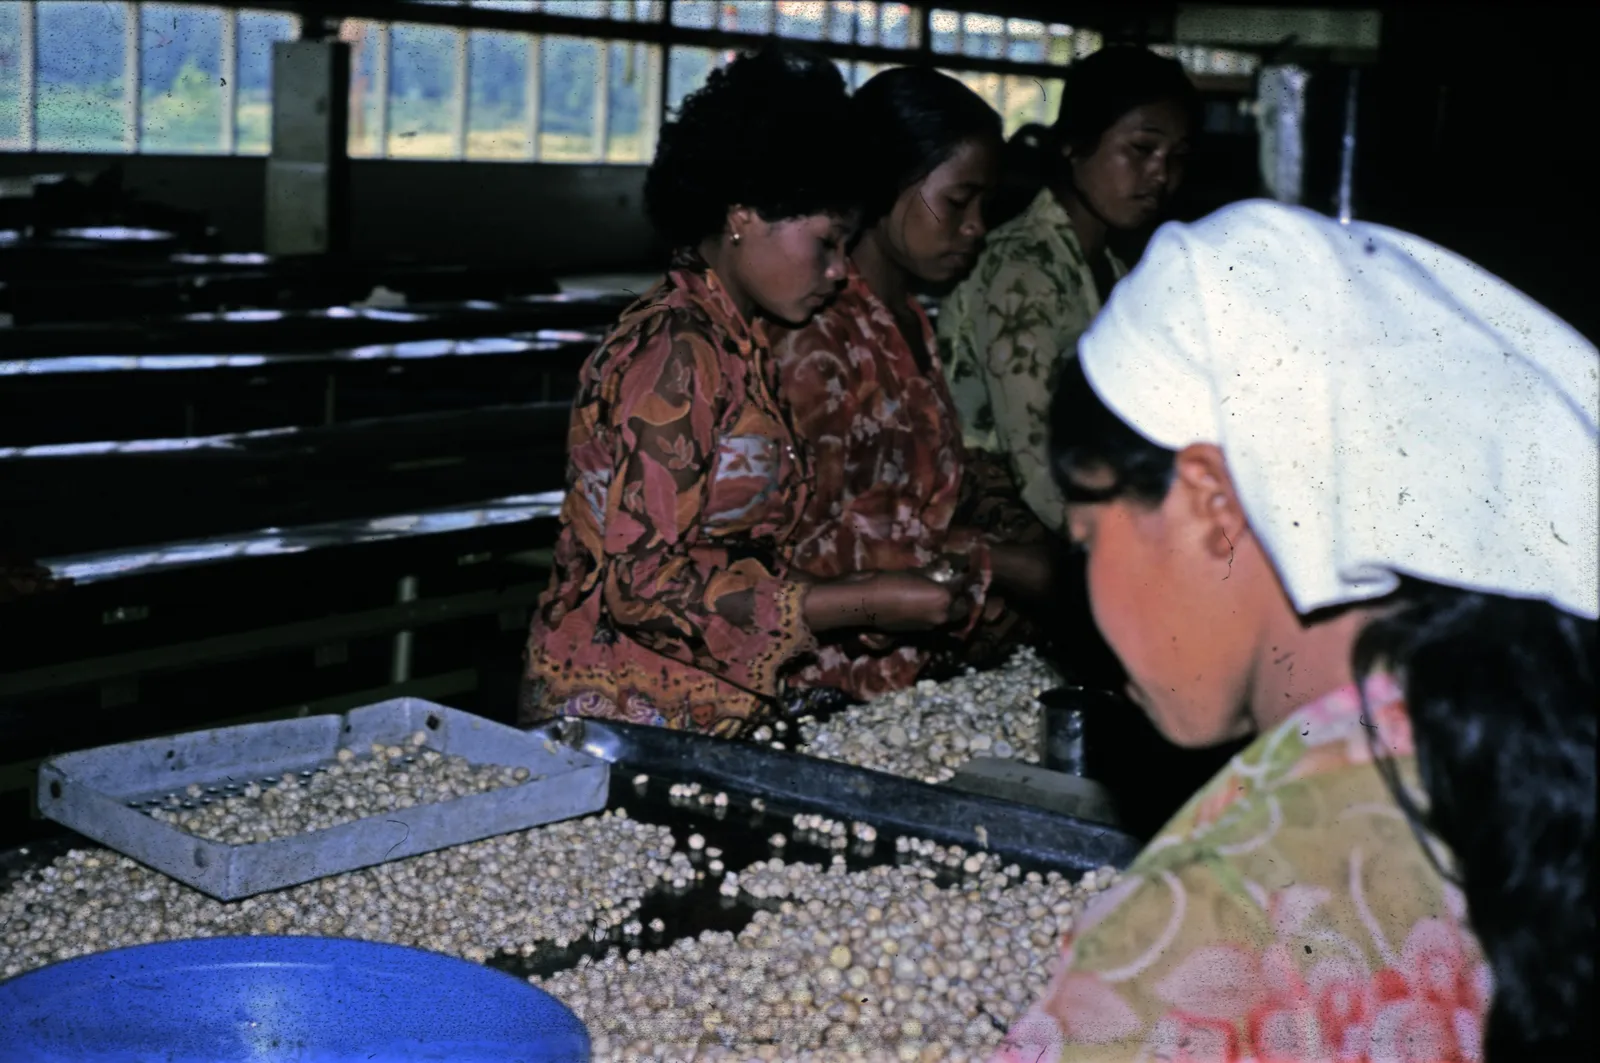
Women sort and trim harvested button mushrooms in trays at a grading table, PT Dieng Djaya farm, Wonosobo, Central Java (archival, 1979). Downloaded as the 3840px Commons JPEG render; original is 4892x3249 image/tiff (95 MB).
Women trimming and grading harvested button mushrooms at a long sorting table in Indonesia, in an older photograph. Trimmings and rejects leave at this table, so fewer kilograms are sold than were picked. Photo: Steijlen, Fridus, CC BY 4.0. Source
Part 03

Published ranges to check your inputs against, not to copy

These figures come from ICAR-DMR and NHB documents. They are biological and planning inputs, not prices or earnings. Put the lower end of each range into your first plan, and replace it with your own crop records as soon as you have them.

Button yield, long method compost10 to 15 kg per 100 kg compostICAR-DMR manual, Table 7.1.
Button yield, short method compost18 to 25 kg per 100 kg compostSame table. It lists indoor compost at 20 to 30.
Lowest strain yield in NHB's table14 to 16 kg per 100 kg compostStrain S-11, under Indian conditions.
Highest strain yield in NHB's table22 to 27 kg per 100 kg compostStrain DMR-NBS-5, under Indian conditions.
Crops per room per year in the manual's model6 crops of 60 daysControlled rooms using indoor compost. Some seasonal growers take a single crop in the season.

Sources: ICAR-DMR manual, 2011 · NHB DPR model, 2018

Part 04

Price comes from a dated rate paid by a named buyer

Revenue is kilograms sold multiplied by the rate actually realised, so the price needs the same care as the cost sheet. A figure read online, a neighbour's opinion or a price printed in an old model report is not evidence for your town and your grade.

Build the record instead. For each possible buyer, such as a commission agent, vegetable retailer, hotel, caterer, processor or household customer, write the name, phone number, the quantity a week they can take, the pack and grade they want, the rate they paid last week with its date, and their payment terms. Repeat on the same weekday for three weeks.

Then work out net realisation: the rate less commission, packing and transport, divided by the kilograms sold. Deduct those selling costs in one place only, here or in the cost sheet.

Shelf life decides how far away a buyer can be. The ICAR-DMR manual gives fresh oyster mushrooms a shelf life of 24 to 48 hours even at room temperature, so a buyer beyond that reach is not part of your market.

Source: ICAR-DMR manual, 2011

From a buyer's rate to the price in your plan

  1. Name the buyerAgent, retailer, hotel, processor or household, with a phone number.
  2. Write the rateGrade, pack, weekly quantity, rate paid, its date and the payment terms.
  3. RepeatThe same weekday, three weeks running.
  4. Net itTake off commission, packing and transport, then divide by kilograms sold.
  5. Check the reachKeep only buyers the crop can reach within its shelf life.
Part 05

Working capital: count the days between paying out and being paid

A plan can show a surplus for the year and still run out of cash in the second month. Money leaves early, for compost or straw, spawn, casing, fuel and wages. It comes back late, after the crop is picked and after the buyer's credit period.

The ICAR-DMR manual shows how long that gap can be. From one tonne of dry straw, an oyster crop is harvested in 45 to 60 days, while button mushrooms take 80 to 100 days including compost preparation. Add the days your buyer takes to pay.

Lay the payments and receipts on a weekly calendar through preparation, growing, harvest and collection. Include the next batch, because its inputs fall due before the last crop's money arrives. The lowest point of the running balance is the starting figure for working capital. Add a reserve for one crop going wrong.

Keep subsidy out of this calendar. The MIDH guideline describes its assistance for mushroom production, spawn and compost units as credit linked back ended subsidy (Annexure V, item III). It follows the spending and the checks, so it cannot pay for spawn in month two.

Sources: ICAR-DMR manual, 2011 · MIDH guidelines, 2025

From the first payment out to the first payment in

  1. Pay for inputsStraw or compost, spawn, casing, bags and fuel are paid before the crop starts.
  2. Grow45 to 60 days for an oyster crop from dry straw; 80 to 100 days for button, including compost.
  3. Harvest and invoiceKilograms leave the farm, but an unpaid invoice is not cash.
  4. CollectThe buyer pays after the agreed credit period.
  5. Next batchIts inputs are due before the last crop's money has cleared.
Part 06

Decide on the weak case, not the best one

Change one input at a time to see what drives the result, then combine the difficult cases. The model is allowed to say: do not build this yet.

IfThe plan only works at the top of a published yield range.
ThenRework it at the bottom of the range and at a lower price before going any further.
IfNet price per kilogram is not above variable cost per kilogram.
ThenSelling more will never cover fixed costs. Break-even kilograms are fixed cost for the period divided by net price less variable cost per kilogram, and here that division has no answer. Fix price or cost first.
IfA 10 per cent fall in capacity use or in sales, or a 10 per cent rise in raw material cost, turns the result negative.
ThenThe project is fragile. These are the three cases in the sensitivity table of NHB's 2018 model report; strengthen the weakest input before borrowing.
IfThe cash calendar stays positive only if subsidy arrives on a set date.
ThenBuild a case with no subsidy and a case with a delayed start. Fund the gap from your own money or an agreed working capital limit.
IfLosing one whole crop would stop your loan instalments.
ThenHold a reserve, reduce the size, or run a small pilot and record it before you build.

Sources: NHB DPR model, 2018 · ICAR-DMR manual, 2011

Part 07

Cost sheet mistakes that make a farm look better than it is

Common mistakeLeaving family and owner labour out of the cost sheet.

Do this insteadValue it at the local wage. Otherwise cost per kilogram is too low, and the farm could not pay anyone to do that work in your place.

Common mistakeGiving a bank a cost of production printed in an old folder or manual as today's cost.

Do this insteadA printed figure belongs to the year and the model of the document that printed it. Use current quotations and your own bills.

Common mistakeCounting harvested kilograms as sold.

Do this insteadOnly kilograms a buyer accepted are sales. Keep rejected and unsold kilograms on their own line.

Common mistakeTreating a sales invoice as money in hand.

Do this insteadAn unpaid invoice is money owed to you. Keep it on the cash calendar until it is collected.

Source: ICAR-DMR manual, 2011

Keep exploring

Every part of this topic.

Choose the stage, material or decision you need to understand next.

01

Mushroom farming business models

Compare growing, wholesale, retail, processing, compost, spawn and integrated models without assuming every vertical fits every operator.

02

Mushroom farm feasibility

Assess biological, climate, technical, infrastructure, raw material, market, financial, operator and risk dimensions separately.

03

Mushroom farm investment

Separate land, project assets, pre-operative expense, contingency and working capital with dated evidence.

04

Capital cost planning

Structure civil, mechanical, electrical, refrigeration, movable equipment and opportunity cost without treating cost norms as quotations.

05

Operating cost planning

Map production inputs, utilities, labour, distribution, farm operations and administration by cost behavior.

06

Working capital for mushroom farms

Understand inventory, crop work in process, receivables, cash buffer and supplier credit before revenue returns.

07

Mushroom production cost

Trace annual operating cost back to the crop unit, room, batch, bag, bed, compost tonne or substrate kilogram.

08

Cost per saleable kilogram

Calculate variable, operating and fully loaded cost using sold saleable production rather than theoretical capacity.

09

Revenue and realized price

Model grades, channels, sell-through, credit, bad debt, processing recovery and unsold product without confusing retail listings with farm-gate realization.

10

Mushroom pricing decisions

Work from dated local market evidence, grade, channel, quantity and payment terms instead of a timeless price claim.

11

How to check mushroom buyers and market demand

Record named buyers, weekly capacity, expected price, credit terms, quality requirements, contact status and evidence confidence.

12

Mushroom farm profitability

Separate revenue, contribution, fixed operating cost, finance, depreciation and pre-tax result with clear definitions.

13

Mushroom farm break-even

Understand break-even quantity, realized price, yield and room utilization through contribution margin.

14

Mushroom farm cash flow

Follow owner capital, loans, receipts, capex, inputs, labour, utilities and debt service month by month.

15

Financing a mushroom farm

Compare own capital, term debt, working-capital borrowing and mixed finance without recommending an unverified loan product.

16

Mushroom farm risk register

Identify biological, technical, input, market, financial, operational and regulatory risks plus single-point failures.

17

Pilot, scale and expansion gates

Move from repeatable crop and market evidence to positive unit economics, capability, working capital and phased scale.

18

Financial sensitivity analysis

See how yield, price, electricity, inputs, labour, rejection, utilization, crop loss and interest alter the result.

19

Mushroom economics case studies

A governed library for dated, documented and limitation-aware cases in original-year rupees.

20

Button mushroom business models

Compare seasonal production, purchased compost, own compost and integrated controlled farms by room, crop and farm.

21

Oyster mushroom business models

Compare seasonal low-cost, controlled fresh and documented dried-product pathways using local substrate and market evidence.

22

Milky mushroom business models

Model warm-season and controlled production with casing labour, fresh-market evidence and quality loss.

23

Paddy straw mushroom business models

Model seasonal local production with rapid route-to-market, rejection and unsold-product consequences.

24

Shiitake business models

Keep log and sterile synthetic-block systems separate across cycle time, controlled fruiting, fresh sales and drying.

Go deeper

Technical reference, records and tools.

Detailed crop-stage information, parameters, diagrams and specialist tools are kept together below. This material retains its source conditions and review limits.

Open the complete technical reference

Economics, feasibility and decision intelligence

How to work out mushroom farming cost and profit

Understand investment, operating cost, production, market risk, working capital and profitability before committing capital.

Run feasibility check
Prices
Dated or left blank
Defaults
Visible and editable
Subsidy
Never operating revenue
Decision
Can be no-go

Start from where you are.

24 governed routes in this planning system.

One canonical page per intent, linked back to technical causes.

Mushroom farming business models

Compare growing, wholesale, retail, processing, compost, spawn and integrated models without assuming every vertical fits every operator.

Mushroom farm feasibility

Assess biological, climate, technical, infrastructure, raw material, market, financial, operator and risk dimensions separately.

Mushroom farm investment

Separate land, project assets, pre-operative expense, contingency and working capital with dated evidence.

Capital cost planning

Structure civil, mechanical, electrical, refrigeration, movable equipment and opportunity cost without treating cost norms as quotations.

Operating cost planning

Map production inputs, utilities, labour, distribution, farm operations and administration by cost behavior.

Working capital for mushroom farms

Understand inventory, crop work in process, receivables, cash buffer and supplier credit before revenue returns.

Mushroom production cost

Trace annual operating cost back to the crop unit, room, batch, bag, bed, compost tonne or substrate kilogram.

Cost per saleable kilogram

Calculate variable, operating and fully loaded cost using sold saleable production rather than theoretical capacity.

Revenue and realized price

Model grades, channels, sell-through, credit, bad debt, processing recovery and unsold product without confusing retail listings with farm-gate realization.

Mushroom pricing decisions

Work from dated local market evidence, grade, channel, quantity and payment terms instead of a timeless price claim.

How to check mushroom buyers and market demand

Record named buyers, weekly capacity, expected price, credit terms, quality requirements, contact status and evidence confidence.

Mushroom farm profitability

Separate revenue, contribution, fixed operating cost, finance, depreciation and pre-tax result with clear definitions.

Mushroom farm break-even

Understand break-even quantity, realized price, yield and room utilization through contribution margin.

Mushroom farm cash flow

Follow owner capital, loans, receipts, capex, inputs, labour, utilities and debt service month by month.

Financing a mushroom farm

Compare own capital, term debt, working-capital borrowing and mixed finance without recommending an unverified loan product.

Mushroom farm risk register

Identify biological, technical, input, market, financial, operational and regulatory risks plus single-point failures.

Pilot, scale and expansion gates

Move from repeatable crop and market evidence to positive unit economics, capability, working capital and phased scale.

Financial sensitivity analysis

See how yield, price, electricity, inputs, labour, rejection, utilization, crop loss and interest alter the result.

Mushroom economics case studies

A governed library for dated, documented and limitation-aware cases in original-year rupees.

Button mushroom business models

Compare seasonal production, purchased compost, own compost and integrated controlled farms by room, crop and farm.

Oyster mushroom business models

Compare seasonal low-cost, controlled fresh and documented dried-product pathways using local substrate and market evidence.

Milky mushroom business models

Model warm-season and controlled production with casing labour, fresh-market evidence and quality loss.

Paddy straw mushroom business models

Model seasonal local production with rapid route-to-market, rejection and unsold-product consequences.

Shiitake business models

Keep log and sterile synthetic-block systems separate across cycle time, controlled fruiting, fresh sales and drying.

Profitability is an operational outcome.

Yield side

Compost quality + spawn quality + climate + disease + skill

Yield → saleable production → revenue
Cost side

Power + labour + compost + packaging + transport + finance

Cost → contribution → operating result

The model can say: do not build this yet.

No guaranteed return, monthly-income promise, timeless market price, assumed subsidy or 100% utilization is published.

Read the evidence

Sources & review.

Editorial update: 2026-08-23. Independent technical review is not recorded for this entry.

Source links for the expanded learning chapters are listed in the handbook above. The foundation summary itself is not independently reviewed.

Reading a source is not the same as applying its instructions to every farm. Confirm species, strain, crop stage, system, region and publication date. Old chemical recommendations are not current-use instructions.

See something that needs correcting? Tell us →

Quick answers · Follow the full explanation

Questions to resolve before your next step.

These short answers introduce the detailed guides. Keep each guide’s sources, conditions and review limits with its advice. Answer summaries updated 2026-09-20; this is not a new independent technical review.

What is the difference between mushroom revenue and profit?

Revenue is the value of product sold, not total harvested weight multiplied by an advertised retail price. Profit also accounts for the relevant production, selling and fixed costs. Keep cash collection, loan payments and working capital visible: an accounting surplus does not mean cash is available for the next crop.

Start with evidence of saleable demand →

Can an online calculator tell me what a farm will earn?

A calculator can show how your stated assumptions interact. It cannot verify future yield, selling price, energy cost or buyer payments. Retain the records behind each input and compare downside, base and upside scenarios. Review the tool’s formula, scope and evidence status before using its output.

Explore the educational feasibility model →

How do I turn a cost estimate into a comparable project brief?

Separate the production model, civil works, equipment, utilities, pre-operative costs and working capital. State inclusions, exclusions, capacity assumptions and the quotation date. Send the same scope to prospective suppliers so differences in price can be traced to differences in delivery.

Prepare a MushroomWale quotation enquiry →